USDA’s Rural Housing Service published a final rule on 29 October 2026 (FR Doc. 2026-22038) amending the Single Family Housing Guaranteed Loan Program (7 CFR part 3555). It takes effect on 28 December 2026. The program guarantees private lenders’ mortgages to low- and moderate-income buyers in eligible rural areas.
What changes
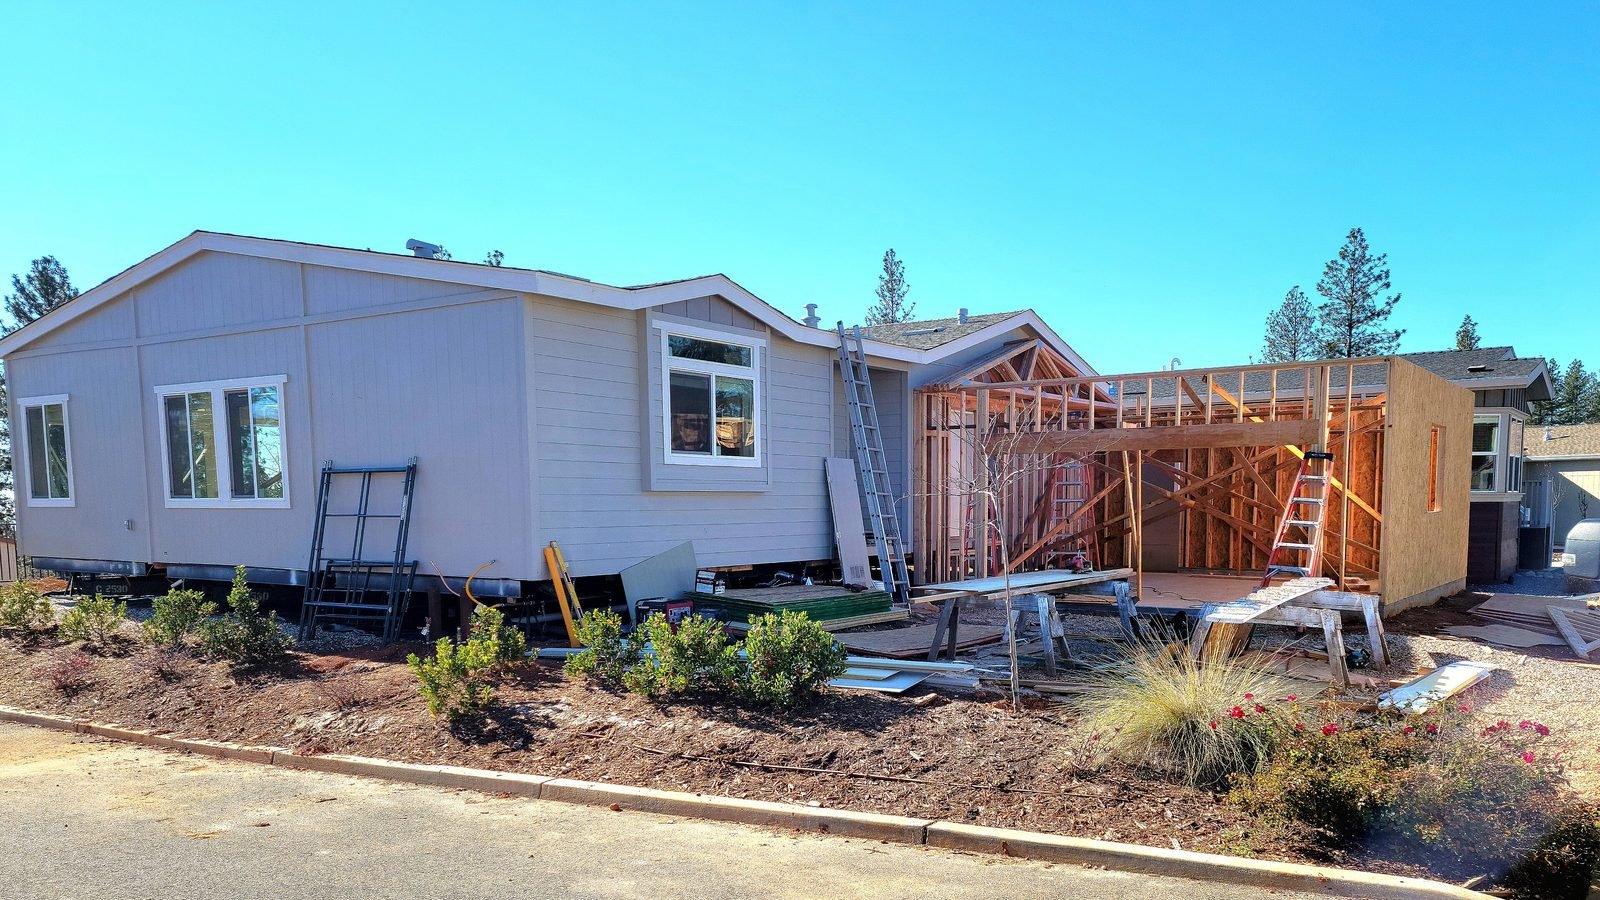
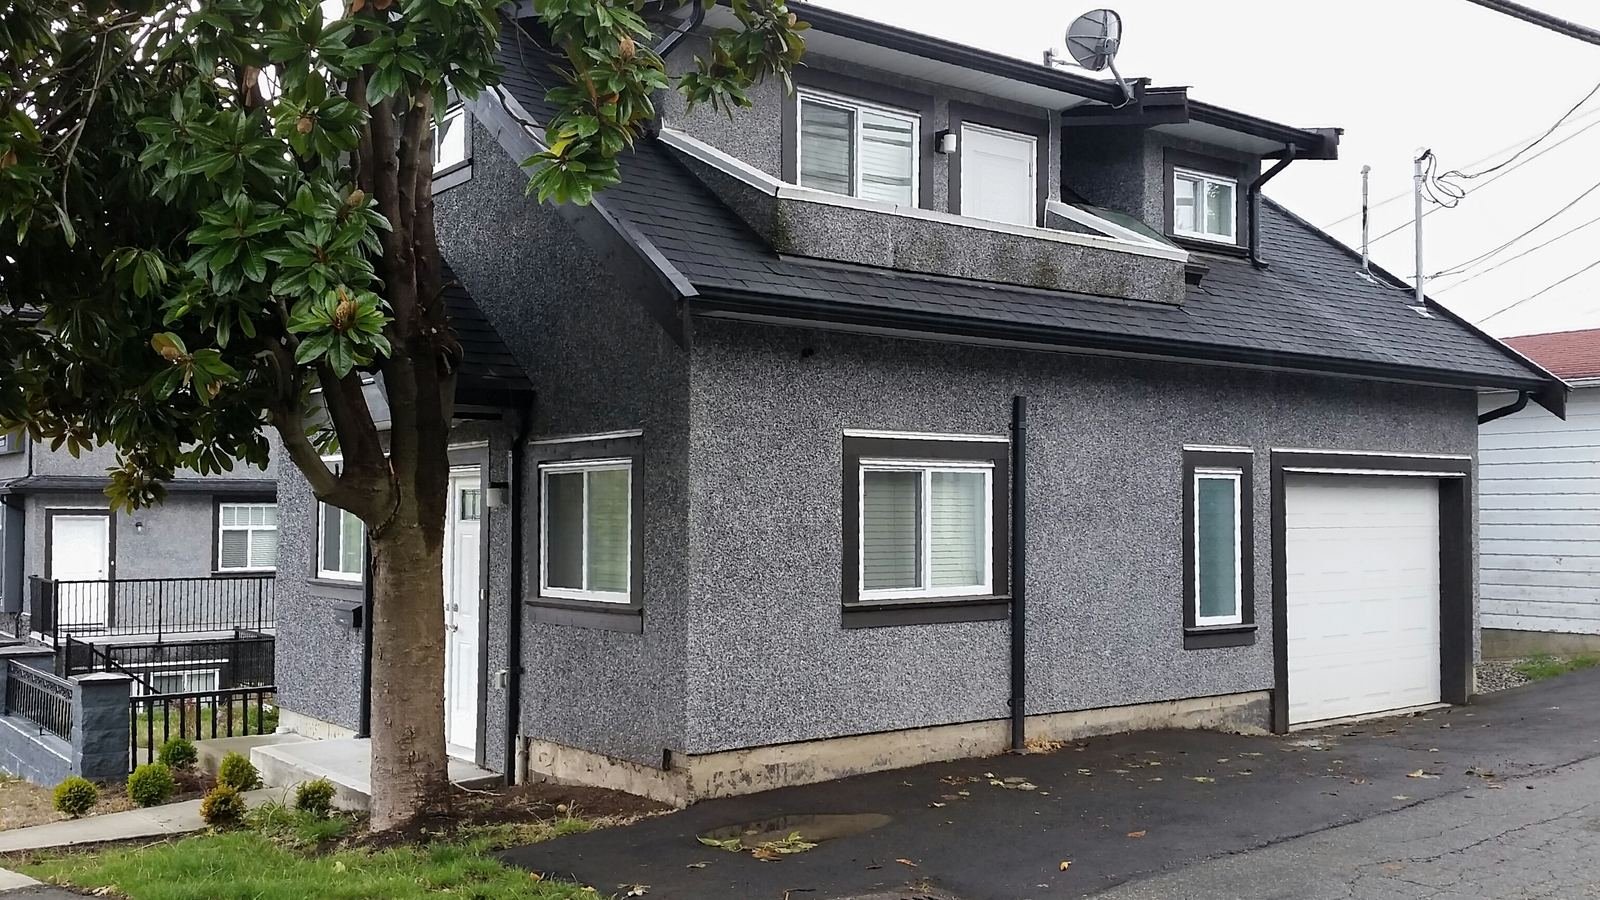
- Accessory dwelling units: the program previously barred financing land or buildings used principally for income. That bar will no longer apply to an otherwise qualifying home that “contains, or will contain, a single or multiple accessory dwelling units.”
- Home businesses: homes with design features for a home-based business, “such as childcare, product sales, or craft production,” become eligible, as long as they do not need commercial real-estate features. Properties used principally for income, farming or commercial enterprise remain ineligible.
- Definitions: an ADU is a habitable unit within or detached from the house, “subordinate in size,” with separate entry, that together with the house is a single real-estate interest. It must meet the program’s “living unit” standard (water, sanitation, heat, hot water, electricity, a bathroom and kitchen facilities).
What does not change
USDA declined commenters’ requests to let lenders count expected ADU rent when qualifying borrowers. It says potential ADU income cannot be verified as stable and “will not include it in income calculations.” Buyers must still qualify on their own income. The rule adopts the March 2026 proposal (91 FR 15914) without changes; USDA received comments from 28 respondents, 19 of them supportive.
“ADUs also provide borrowers with a means to generate additional income.” — USDA Rural Housing Service final rule, 29 October 2026
Bottom line
A small eligibility change with direct effect for rural buyers: from 28 December, USDA guarantees can cover homes with rentable accessory units and home-business features. It sets no new money and does not change underwriting.