Lean score (−100 far left to +100 far right; 0 = centre) reflects how this article frames the issue — language emphasis and narrative tilt — not a verdict on truth. Data-first pieces with balanced sources trend toward centre. Disclosed for transparency; not a ranking of correctness.
Lean score (−100 far left to +100 far right; 0 = centre) reflects how this article frames the issue — language emphasis and narrative tilt — not a verdict on truth. Data-first pieces with balanced sources trend toward centre. Disclosed for transparency; not a ranking of correctness.
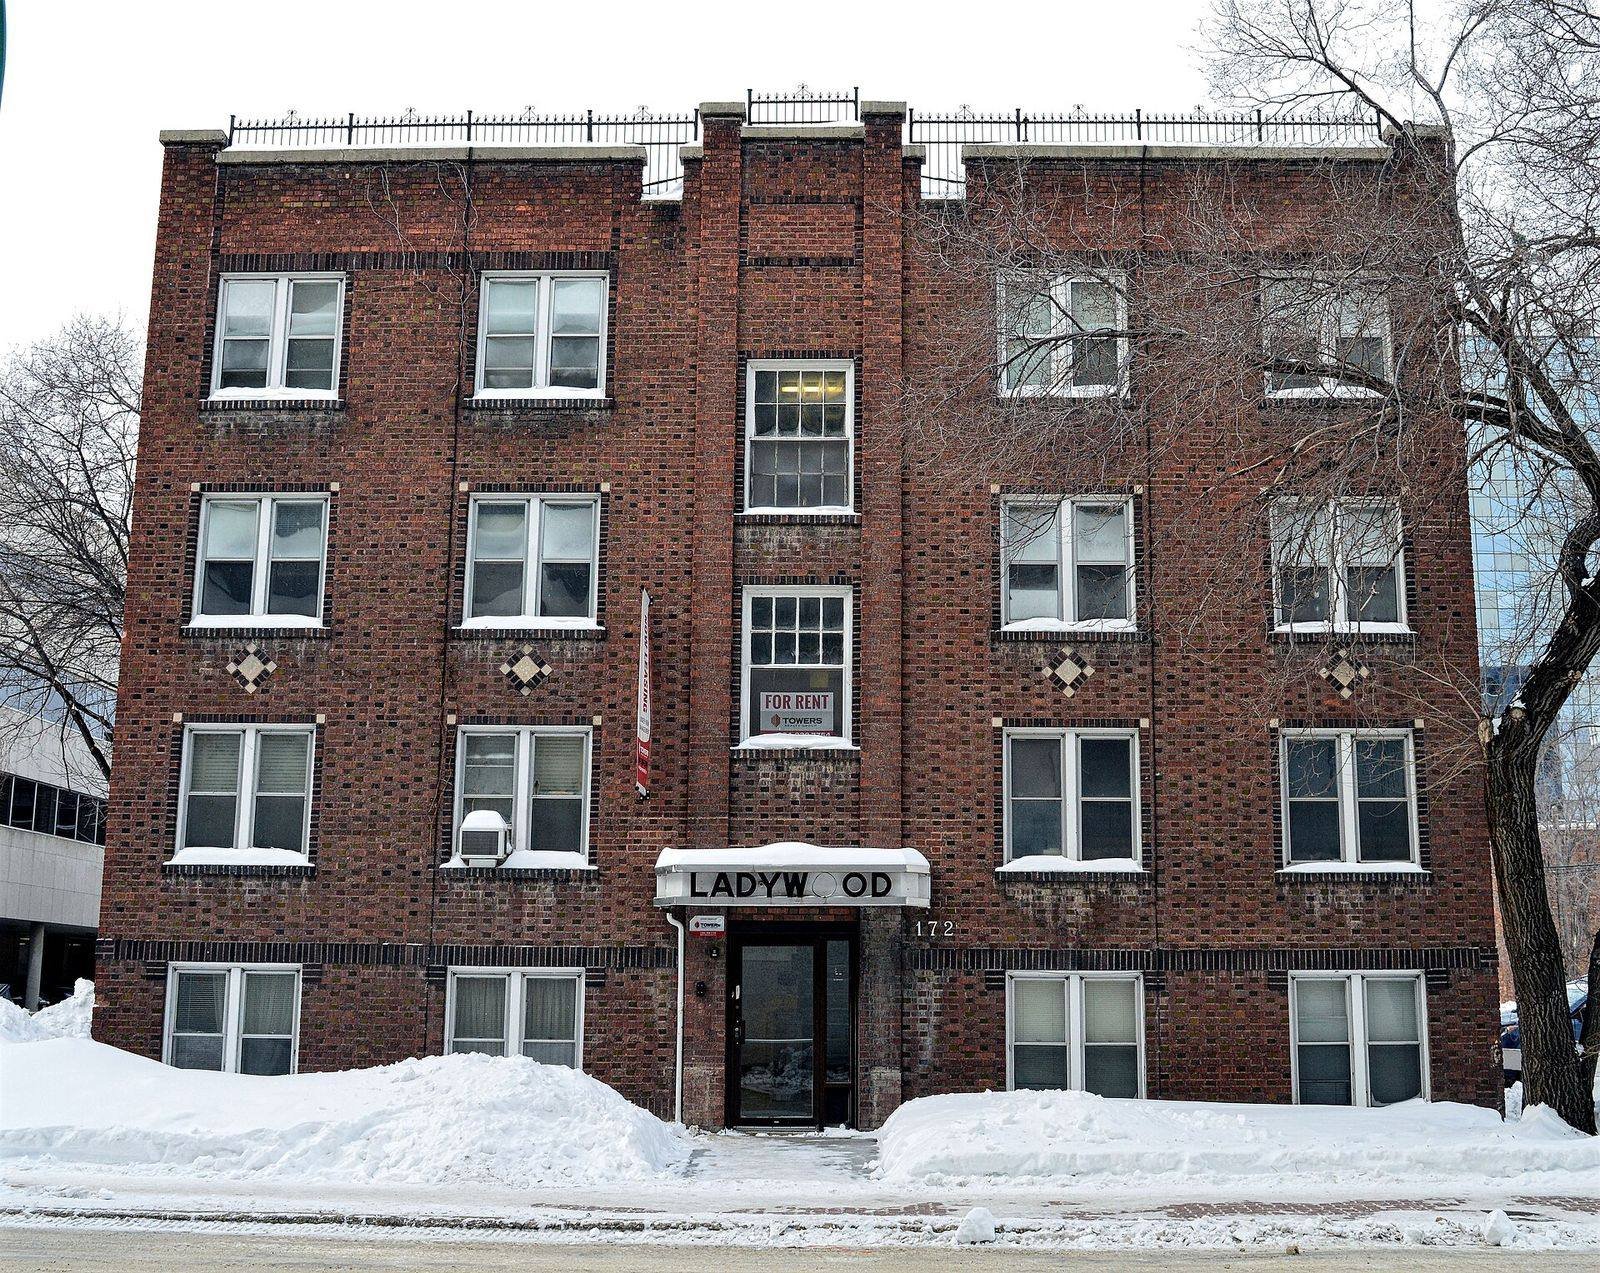
An apartment building in Winnipeg. Photo: Darrell Neufeld, public domain
Ownership affordability gets the headlines; renters feel the shortage first. CMHC’s Rental Market Survey continues to show purpose-built apartment vacancy rates in Toronto, Vancouver, and other major census metropolitan areas well below levels that historically moderated rent growth.
New purpose-built supply is rising in some cities, but absorption from population growth and conversion dynamics keep markets tight. Secondary rental (condos offered for rent) behaves differently from purpose-built stock — mixing them without labels confuses policy.
A 1% vacancy rate is not a market — it is a queue.
Citizen impact: Tight vacancy correlates with above-average rent increases in CMHC tables. Tenant protection rules change the distribution of pain; they do not create apartments.
Municipal zoning that allows more multi-unit near jobs and transit is the long fuse; immigration and household formation are the demand side. Both belong in any honest affordability plan.
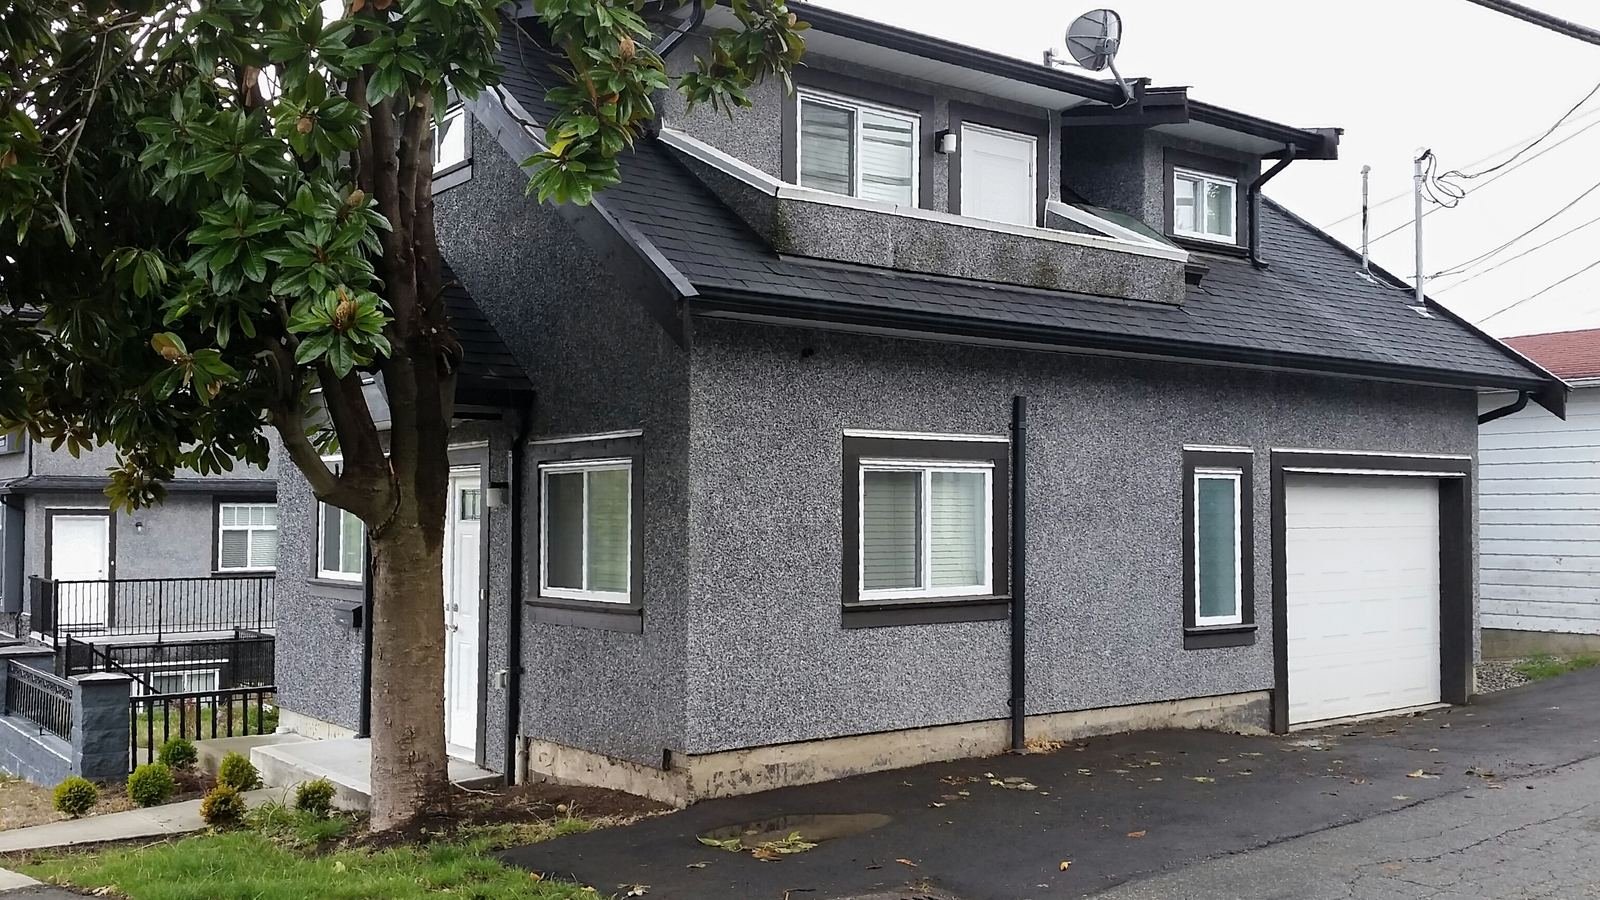
A final rule in today’s Federal Register lets the Single Family Housing Guaranteed Loan Program back properties with one or more income-producing accessory dwelling units and homes designed for home-based businesses such as childcare or crafts. Lenders still cannot count expected ADU rent as borrower income.
Signed 22 October and published in today’s Federal Register, the order asks the FHFA to have Fannie Mae and Freddie Mac test proactive cancellation of mortgage insurance using automated home valuations, to make their title-insurance waiver pilot for refinances a nationwide program, and to pass savings to borrowers. It also sets up a task force on manufactured and factory-built homes and tells USDA and VA to cut rates on their direct home loans. Most steps depend on the FHFA director’s judgment and on later agency action.
In a Voluntary Compliance Agreement signed 20–21 October, Multnomah County, Oregon, and its Homeless Services Department agree to remove points for an applicant’s interest in culturally specific services within seven days and to rename “English as a second language” as “language barriers”. They must rescore pending households and reset Priority Housing Pool thresholds. The county denies the allegations, and the agreement is not a HUD finding.